

Huawei has strengthened its leadership in China’s smartphone market in the third quarter of 2026, increasing shipments 17.3 percent year on year and expanding its market share to 21.1 percent. Apple ranked second, while OPPO, vivo, Xiaomi and Honor recorded shipment declines as rising component costs and higher handset prices weakened demand.

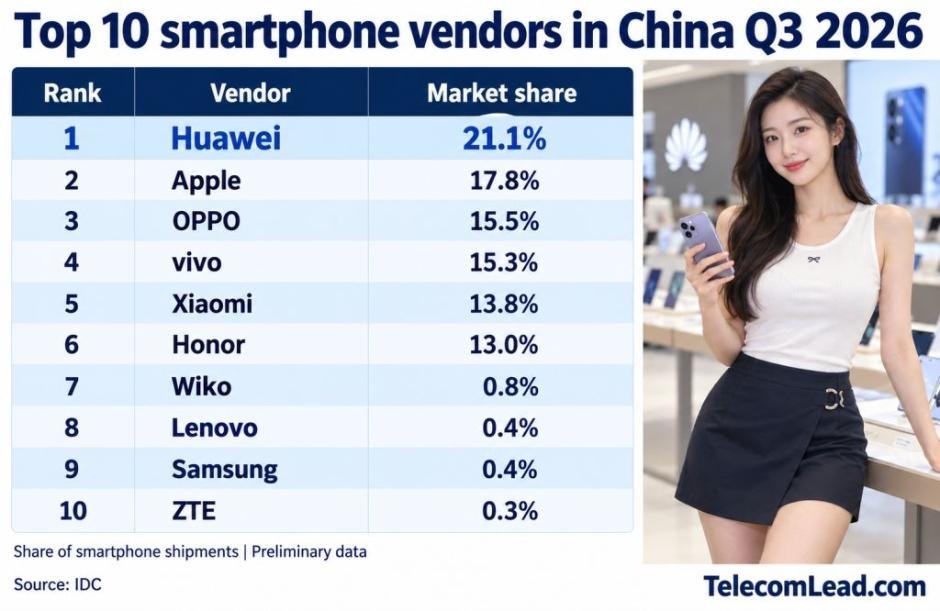
China’s smartphone shipments totaled approximately 57.9 million units, down 15.4 percent year on year, according to preliminary IDC data. Huawei was the only major vendor to achieve double-digit annual growth, widening its lead in an increasingly difficult market.
Huawei Expands Its Lead With 21.1% Market Share
IDC report on China’s smartphone market Q3 2026 indicated that Huawei delivered the strongest annual performance among China’s leading smartphone vendors. Its market share increased by 5.9 percentage points, from 15.2 percent to 21.1 percent, while shipments grew despite the wider market contraction.
IDC attributed Huawei’s performance to its diverse product formats and relatively restrained price increases. Together, these helped the company maintain demand as consumers faced more expensive replacement devices.
However, Huawei’s shipments fell 17.6 percent from the previous quarter. Its annual growth therefore shows a stronger position than a year earlier, while the sequential decline indicates that it still faced the quarter’s broader demand pressures.
Huawei’s lead over Apple reached 3.3 percentage points, compared with a 0.6-point deficit a year earlier. This reversal highlights the scale of Huawei’s improvement in China’s vendor rankings.
Apple Gains Share Despite a 4.3% Shipment Decline
Apple secured second place with 17.8 percent market share, up from 15.8 percent a year earlier. Its shipments declined 4.3 percent year on year, substantially less than the overall market’s 15.4 percent contraction.
The distinction matters: Apple gained share because its shipments held up better than the market, although its unit volume still fell.
According to IDC, reception for Apple’s newly launched phones exceeded expectations. However, fewer models in this year’s lineup limited shipment volume. Apple also recorded a 15.1 percent sequential decline, showing that stronger launch reception did not translate into overall quarterly growth.
OPPO Moves Ahead of vivo as Both Lose Volume
OPPO ranked third with 15.5 percent market share, narrowly ahead of vivo at 15.3 percent. A year earlier, vivo held 17.2 percent compared with OPPO’s 15.9 percent.
OPPO’s shipments declined 17.6 percent year on year, while vivo recorded a steeper 24.9 percent reduction. Their market shares fell by 0.4 and 1.9 percentage points, respectively.
The figures show that OPPO’s move ahead of vivo resulted from a smaller shipment decline. OPPO’s reported performance covers OnePlus and realme, while vivo’s figures include iQOO.
Sequentially, OPPO shipments fell 15.5 percent, and vivo shipments decreased 16.1 percent, leaving both vendor groups under pressure.
Xiaomi Shows Greater Sequential Stability
Xiaomi held fifth place with 13.8 percent market share, down from 14.7 percent in Q3 2025. Shipments declined 20.4 percent year on year.
However, Xiaomi’s quarter-on-quarter decline was limited to 2.2 percent, the smallest sequential reduction among the top five vendors. This suggests better short-term shipment stability than Huawei, Apple, OPPO and vivo, although its annual performance remained weak.
Xiaomi’s figures illustrate why annual and sequential comparisons should be assessed separately: a relatively stable quarter can coexist with a substantial decline against the previous year.
Honor Posts 0.9% Sequential Growth
Honor ranked sixth with 13 percent market share and was the only vendor among the leading six to increase shipments from the previous quarter.
Its 0.9 percent sequential growth provided an early sign of stabilization. Nevertheless, shipments remained 24.2 percent below the year-earlier level, and market share declined from 14.4 percent.
Honor’s improvement therefore represents a modest quarterly rebound, with an annual recovery still to be established.
Smaller Smartphone Vendors Face Sharper Declines
The pressure extended beyond the leading brands. Wiko’s shipments fell 74 percent year on year, Samsung’s declined 45 percent, and ZTE’s decreased 52 percent.
Lenovo was an exception, recording 1.1 percent annual growth, although its market share remained just 0.4 percent.
Samsung more than doubled shipments sequentially, with 106.5 percent growth, but that increase came alongside a substantial annual decline and a small market share. The two comparisons point to a quarterly rebound from a low base rather than a broad recovery.
Calculated from IDC’s rounded figures, the six leading vendors accounted for approximately 96.5 percent of China’s smartphone shipments, up from 93.2 percent a year earlier. This indicates further concentration around the largest brands.
Higher Smartphone Prices Shape the Outlook
China’s market contraction accelerated from approximately 4 percent in the first half of 2026 to 15.4 percent in the third quarter. IDC linked the deterioration to rising memory and other component costs, higher retail prices and changes in product configurations.
These pressures are extending replacement cycles and making price increases harder for vendors to absorb or pass on. IDC expects difficult conditions to continue through Q4 2026 and much of 2027.
For smartphone vendors, the competitive advantage increasingly depends on maintaining product appeal while limiting price increases. Huawei’s annual growth and Apple’s market-share gain show stronger resilience, while Honor’s modest sequential improvement offers a more limited sign of recovery.
BABURAJAN KIZHAKEDATH